Market overview of the Processed Alumina And Aluminum Market
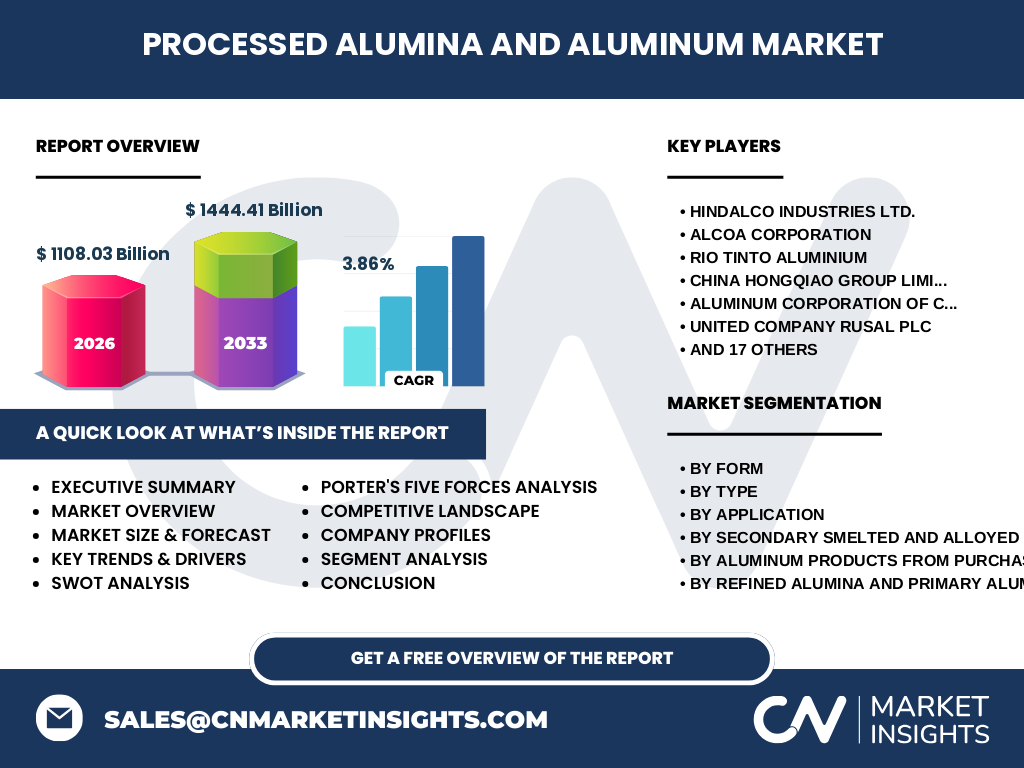
Our analysis indicates that the Processed Alumina And Aluminum Market is valued at 1108.03 Billion in 2026. This foundational sector converts bauxite ore into refined alumina and high-performance aluminum products, serving as the macroeconomic backbone for global manufacturing, energy infrastructure, and lightweight transportation networks.
Structural Growth Drivers and Market Restraints
The market is propelled by surging demand for lightweight automotive architecture and green energy infrastructure. However, growth is restrained by stringent environmental mandates enforced by bodies like the International Aluminium Institute and volatile energy costs required for Hall-Héroult smelting operations.
The Shift Toward Circular Metallurgical Practices
Industry participants are aggressively pivoting toward closed-loop recycling and low-carbon primary production. Recycled aluminum alloys and secondary smelting are capturing capital as automakers demand certified low-carbon aluminum sheets and plates to meet corporate sustainability goals.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted supply chains and shuttered automotive assembly plants, causing temporary demand contraction. Post-pandemic recovery has been robust, driven by stimulus-backed infrastructure spending and a structural rebound in demand for extruded products and primary aluminum ingots.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, featuring global giants like Alcoa Corporation, Rio Tinto Aluminium, and Hindalco Industries Ltd. These industry leaders maintain competitive moats through vertical integration, proprietary smelting technologies, and secure access to captive bauxite reserves.
Executive Summary of Key Industry Findings
Our comprehensive research reveals a projected market valuation of 1444.41 Billion by 2033, expanding at a steady CAGR of 3.86%. Strategic investments in secondary processing and regionalized supply chains represent the primary avenues for margin expansion.
Market Forecast from 2027 to 2033
Driven by accelerating industrialization and EV adoption, the market will scale from 2027 through 2033 to reach 1444.41 Billion. This expansion represents a steady 3.86% CAGR, underpinned by sustained consumption of aluminum bars, rods, and structural extrusions.
Segmentation Analysis by Form, Type, and Application
The market segments into forms such as primary ingots, sheets, foils, and cables; types including refined alumina and secondary alloys; and applications spanning automotive and manufacturing. Each segment plays a critical role in balancing cost, strength-to-weight ratios, and formability.
Geographic Distribution and Regional Performance
Asia-Pacific dominates consumption due to massive manufacturing hubs in China, while North America and Europe focus on high-value aerospace rolled products and stringent carbon-compliance frameworks. Regional performance closely mirrors local automotive output and heavy industrial activity.
In-Depth Regional Review of Processing Hubs
Key regional clusters leverage proximity to major ports and cheap energy sources. Gulf producers like Emirates Global Aluminium and Aluminum Bahrain (ALBA) utilize competitive power tariffs to export high-purity metal to deficit regions in Europe and the Americas.
Company Profiles and Strategic Positioning
Leading innovators such as Novelis Inc., Constellium SE, and Norsk Hydro ASA differentiate themselves through advanced rolling and recycling capabilities. Their strategic focus remains on lightweighting solutions for premium automotive OEMs and sustainable beverage packaging.
Porter's Five Forces Competitive Assessment
Bargaining power of suppliers is moderate due to bauxite resource concentration, while buyer power is high among massive automotive conglomerates. Threat of substitution remains low in structural applications where aluminum's unique strength-to-weight ratio is irreplaceable.
SWOT Analysis of the Alumina and Aluminum Sector
Strengths include infinite recyclability and superior mechanical properties. Weaknesses involve carbon-intensive smelting processes. Opportunities lie in closed-loop EV scrap recycling, while threats stem from tightening carbon border adjustment mechanisms and geopolitical trade tariffs.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from bauxite mining and Bayer-process alumina refining to Hall-Héroult smelting and downstream fabrication. Value concentrates heavily in downstream rolling, extrusion, and closed-loop recycling operations managed by integrated market leaders.
Strategic Investment Insights and High-Potential Areas
Investors should target greenfield recycling infrastructure and low-carbon smelting technologies. Companies possessing advanced alloy development capabilities are best positioned to capture premium margins amid tightening global carbon regulations.
Conclusion and Key Takeaways for Market Stakeholders
The Processed Alumina And Aluminum Market offers durable growth prospects backed by a 3.86% CAGR toward 1444.41 Billion. Success requires adapting to decarbonization mandates and securing resilient, localized supply chains for secondary and primary metals.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary stakeholder interviews with smelter executives, and secondary macroeconomic indicators from organizations like the World Bank and International Aluminium Institute.
Scope of the Report and Coverage Parameters
This report covers global production, trade flows, and consumption trends for refined alumina and aluminum products from 2026 to 2033. Analysis excludes unrefined bauxite mining operations except where upstream integration directly impacts downstream feedstock availability.
Recent Developments and Industry Announcements
Recent strategic moves include major joint ventures focused on green aluminum production, multi-billion-dollar investments in post-consumer scrap sorting facilities, and long-term supply agreements between primary smelters and electric vehicle manufacturers to guarantee low-carbon metal supply.